

JPay

- 36.05K Reviews
- 3.9
- Downloads
- 5,000,000+
Our take on JPay from Appgk
When someone in a correctional facility needs money, a message, or a photo from the outside, the difficult part is often not deciding what to send. It is finding a practical way to complete the whole process without jumping between several unrelated services. That is the problem JPay tries to solve. I reviewed it as a finance app from Jpay Mobile, and I found its value is less about being a general-purpose money tool and more about connecting everyday support with communication for people in custody.
The app is free to install, carries a Teen content rating, and has been available since October 15, 2012. Its audience is clearly substantial: it has passed five million installs, with an average rating of 3.9 from roughly one hundred four thousand ratings and about thirty-six thousand written reviews. Those figures suggest a service many people rely on, while also hinting that the experience can vary depending on the situation, the facility involved, and the task being attempted.
Following one real-world JPay workflow from need to outcome
Starting with a specific need
The best way to understand this app is to begin with a realistic situation. Imagine that a family member wants to help someone in custody with funds and also send a short personal message with a photo. In a normal banking app, sending money and communicating would usually be separate activities. In a normal messaging app, financial support would not be part of the same environment. JPay brings those needs together, so the first step is identifying the person, the facility, and the type of support required.
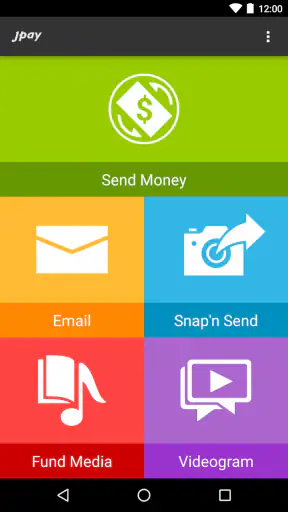
I would not open it casually expecting a broad personal-finance dashboard. It is not designed to replace a bank account, manage household budgets, or compare loans. Its purpose is much narrower and more practical: helping users send money and exchange emails, photos, and related communication with eligible recipients. That focus is useful when the recipient is already connected to the JPay system, but it also means the app makes most sense after you know exactly who you are trying to reach.
Best Parts of JPay
Things to Keep in Mind About JPay
Before starting, I would gather the recipient’s identifying details and check the destination carefully. A small mistake at this stage can create more trouble than it would in an ordinary social app because the transaction and the communication are tied to a correctional setting. My strongest practical advice is to treat the recipient profile as something to verify, not something to select quickly from memory.
Moving through the app instead of improvising
Once the right recipient is located, the workflow becomes more purposeful. For financial support, the user moves toward the money-sending function; for contact, the user switches to email or photo communication. The advantage is that these activities live in one app rather than requiring a separate payment service, a separate messaging platform, and another method for sharing images.
News and Features Related to JPay

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
I like this arrangement for a family member who handles several small responsibilities at once. A person may check the recipient, send funds, then write a message while the reason for the payment is still fresh. That reduces the chance of forgetting the communication part after completing the financial part. It also creates a more human routine: practical help and emotional contact can happen in the same session.
The trade-off is that a combined app can make the process feel more serious than a familiar chat application. There are more consequences to tapping the wrong option, and the user may need to slow down when moving between a message and a financial action. I would avoid rushing through the screens, especially when sending money for a specific purpose such as personal items, phone access, or another approved need.
Don't want to read the full review?
Handling the handoff between sender and recipient
The most important handoff is not from one screen to another. It is from the outside sender to the person inside the facility. A message, photo, or payment passes through a system shaped by the recipient’s location and circumstances, rather than arriving like an ordinary instant message. That changes the user’s expectations. I would think of JPay as a controlled delivery channel, not a live conversation.
This distinction matters when writing. A short, clear message is usually more useful than a long note that depends on immediate replies. I would include the key point near the beginning, avoid making the recipient search through a complicated explanation, and use a photo only when it adds something meaningful. A family update, a child’s school milestone, or a simple picture from home can carry more value than sending images without context.
Screenshots
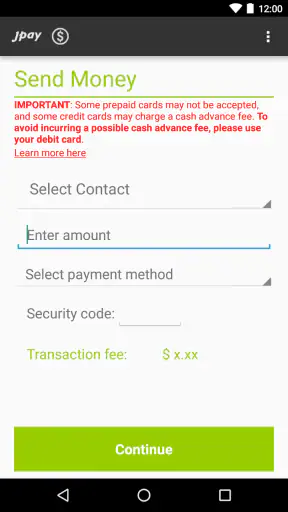
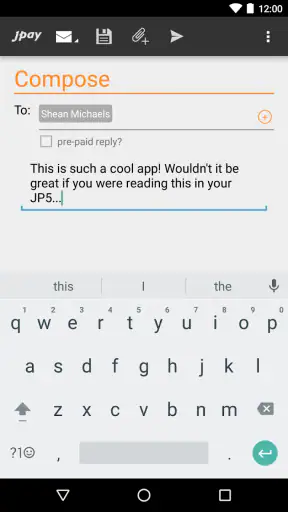
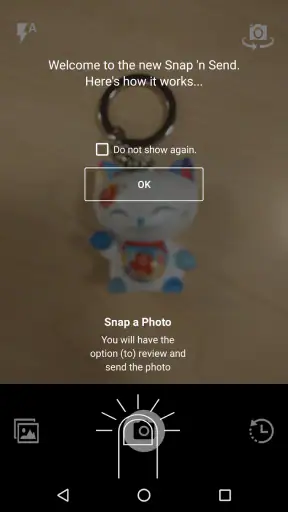
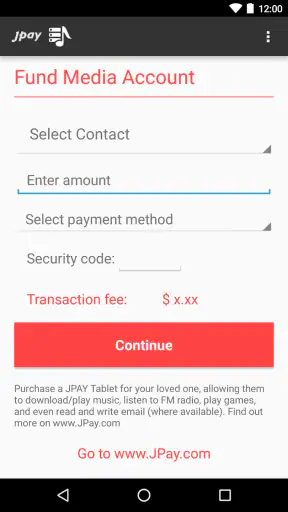
The financial handoff deserves the same care. Sending money is not just a button press; it is a decision about who receives support and what the sender can comfortably afford. I would review the recipient and amount before confirming, then keep a personal note of the purpose. That habit is especially helpful when several family members contribute separately, because it prevents confusion about who sent what and why.
JPay is also more useful when one person takes responsibility for the workflow. If several relatives use different accounts or send overlapping messages, the recipient may receive fragmented information and the family may lose track of payments. A shared family routine—one person checks the profile, another supplies the message, and everyone agrees on the intended support—can reduce duplicated effort even though the app itself does not replace family coordination.
What the completed result feels like
The outcome is a single place for practical and personal contact. A sender can use the finance side to provide support and the communication side to maintain a relationship. That combination is the app’s clearest strength. It recognizes that money sent to someone in custody is rarely the whole story; people also want to explain, encourage, reassure, or simply stay present.
For me, the communication tools make the financial function feel less transactional. Sending funds alone can feel like completing an obligation. Adding a thoughtfully written email or a relevant photo turns the same session into a more complete act of support. This is where JPay differs from a standard money-transfer app: the intended outcome is not only movement of funds, but continued contact around that support.
Still, I would keep expectations realistic. The app is useful for initiating these actions, but it cannot make the recipient’s environment behave like a normal mobile inbox or personal bank account. The recipient’s access and the handling of communication depend on the correctional context. That means the app works best for deliberate, patient contact rather than urgent back-and-forth conversation.
Where the workflow can break
The first point of friction is recipient selection. If the user has incomplete information or chooses the wrong person, the entire process becomes uncertain before money or a message is sent. I would double-check every identifying detail and avoid assuming that a familiar name is enough. This is one of those apps where careful preparation is more valuable than speed.
The second problem is expectation management. Someone accustomed to instant messaging may wonder why a response is not immediate or why a photo exchange does not feel as effortless as it does on mainstream social platforms. JPay’s purpose is specialized, and its communication experience should be judged against the realities of communicating with a person in custody, not against a casual chat app.
A third issue is that the app may not be the best choice for every financial situation. If I only needed ordinary transfers between friends, a bank app or a mainstream payment service would probably be simpler. Those alternatives are built around everyday personal payments, while JPay is valuable precisely because it connects financial support with correctional communication. Choosing the wrong category of tool creates unnecessary friction.
I would also avoid treating the app as a complete record-keeping system for a household. It can support a payment-and-message workflow, but families may still need their own notes to track contributions, dates, intended purposes, and follow-up. That extra step is not glamorous, but it helps prevent misunderstandings when support is regular or shared among relatives.
How it compares with ordinary alternatives
Compared with a bank or general payment app, JPay is more specialized and more relevant when the recipient is in a correctional facility. A bank app may be cleaner for standard transfers, but it does not normally combine that task with emails and photos directed through the same correctional communication environment. If communication is part of the reason for sending support, JPay has a meaningful advantage.
Compared with a social messaging app, JPay is better suited to this particular handoff but less suitable for spontaneous conversation. A social app is designed for quick replies, broad contact lists, and informal sharing. JPay is designed around a specific recipient and a specific institutional setting. I would choose it when the recipient’s access requires it, not because it offers the most flexible messaging experience.
Compared with using separate services, the main benefit is continuity. I can move from a payment task to an email or photo without changing the overall context. The downside is that a problem in one part of the workflow can make the whole session feel blocked. A user who only wants to send a message may still encounter the seriousness and structure of a finance-oriented service, while someone who only wants to send money may not care about the communication tools.
Useful habits for smoother sessions
My first habit would be to prepare the message before opening the app. Writing the important details in a notes app or on paper makes it easier to review the wording and prevents a rushed message from being sent after dealing with the financial part. I would then paste or retype the final version carefully, checking the recipient again before sending.
My second habit would be to separate emotional writing from transaction review. I would write the message, pause, and then review the payment details independently. Combining both decisions in one hurried sequence increases the chance of overlooking an amount or recipient. Treating them as two linked but separate steps gives the workflow a useful safety check.
My third habit would be to use photos with a clear purpose. A photo can make contact feel personal, but sending too many images or images without explanation may make the exchange less meaningful. I would choose one that communicates something the words cannot, then add a short explanation so the recipient understands why it matters.
My fourth habit would be to keep expectations visible for everyone involved. If a family member is waiting for a reply, I would explain that the app is not the same as live chat. If several people are sending support, I would coordinate before opening the payment screen. These small decisions address the handoffs around the app, which are often where confusion begins.
Who will get the most from it
JPay is a strong fit for relatives and friends who regularly need to combine financial help with personal contact for someone in custody. It is especially useful for a person who wants one familiar place for money, email, and photos rather than managing separate tools. The app’s free price also lowers the barrier to trying the workflow, although users should still think carefully about the costs and consequences associated with any financial action before confirming it.
It can also suit a family coordinator. One person may be responsible for checking in, sending a message, and arranging support on behalf of others. In that role, the app’s combination of functions saves context switching and makes it easier to handle a complete contact session. The key is organization: the app helps with the actions, while the family still needs a clear agreement about responsibility.
I would recommend skipping it if your needs are limited to normal banking, budgeting, or casual messaging. It is too specialized for those purposes. I would also hesitate to recommend it to someone who expects instant replies, a broad social network, or the same convenience as a mainstream payment wallet. Its usefulness depends heavily on having a recipient and situation that fit its intended environment.
Device support and long-term practicality
The current version is 26.4.0, and the app requires at least iOS or Android 11. That requirement is worth checking before planning to rely on it, particularly if you use an older phone that still handles banking and messaging apps without trouble. A device that cannot meet the minimum operating-system requirement can interrupt the workflow before recipient selection even begins.
Because this is a finance-related app, I would keep the operating system updated when possible and use a device that I trust for personal and payment information. I would also avoid completing a transaction while distracted, on an unfamiliar device, or through a connection I do not normally use. These are sensible precautions for any financial tool, but they matter more here because the app combines money with sensitive personal communication.
The Teen content rating does not make this a children’s finance app. In practice, the subject matter involves adult responsibilities, family relationships, and financial decisions. I would expect a parent or guardian to explain the purpose before allowing a younger person to use it, especially if that person is helping prepare a message or photo rather than independently managing a payment.
My overall experience with the service
What stayed with me after reviewing JPay is how clearly it serves a specific moment in a person’s life. It is not trying to be everyone’s wallet or everyone’s inbox. Its usefulness comes from bringing together two actions that often belong together when supporting someone in custody: providing practical help and maintaining a personal connection.
The app is not frictionless in the way a general chat app can be, and I would not use it for ordinary payments when a bank application is more appropriate. The recipient-checking step, the institutional handoff, and the need for realistic expectations all require patience. Those are not reasons to dismiss it; they are reasons to use it deliberately.
With a 3.9 average from around one hundred four thousand ratings, JPay presents a mixed but broadly established reputation rather than an unquestioned one. That matches my view: the concept is genuinely useful, but the experience depends on the exact workflow, the recipient, and the user’s ability to slow down at important points.
My recommendation is simple: choose JPay when you need a focused bridge between financial support and communication with someone in custody. Prepare the recipient details, separate the message review from the payment review, coordinate with other family members, and do not expect instant-chat behavior. Used with those expectations, the app can turn a complicated obligation into a more manageable routine. For ordinary banking or casual messaging, I would choose a different tool; for this specific handoff, JPay is a practical option worth considering.
JPay FAQ
What is JPay used for?
JPay is a communication and payment service designed primarily for people who want to stay in contact with incarcerated friends or family members. Depending on the correctional facility, users may be able to send emails, photos, electronic payments, video visits, stamps, or other approved services. Available features are not identical everywhere, so you should check whether the recipient’s facility is supported before creating an account or sending money.
Can I use JPay to send money to an incarcerated person?
In many supported locations, JPay allows users to send money to an incarcerated person’s trust or commissary account. You normally need the recipient’s correct identification details, facility information, and a valid payment method. Fees, transaction limits, processing times, and available deposit options can vary considerably by state or facility. Review the final transaction summary carefully before confirming a payment, since some transfers may not be refundable.
How does JPay email work, and are messages private?
JPay email is not the same as ordinary private email. Messages are routed through the correctional system and may be screened, delayed, rejected, or reviewed according to facility rules. Some facilities require electronic stamps or impose limits on message length and attachments, while photos may need additional approval. Before sending anything, read the applicable communication policies and avoid including content that could violate institutional regulations.
Is JPay available at every correctional facility?
No. JPay’s services depend on agreements with individual correctional departments and facilities, and the available options can differ even between institutions in the same state. A facility may support payments but not email, or offer messaging without video visitation. Use the app or website’s recipient and facility search tools to confirm eligibility before downloading, registering, or entering payment information.
Are there fees for using JPay?
Most JPay services can involve fees, including money transfers, electronic messages, stamps, video visits, or other optional features. The exact cost depends on the service, payment amount, recipient’s facility, and local regulations. Additional restrictions, minimum charges, or transaction limits may also apply. Because prices can change, check the current fee displayed during checkout rather than relying on an older estimate or an unofficial review.











